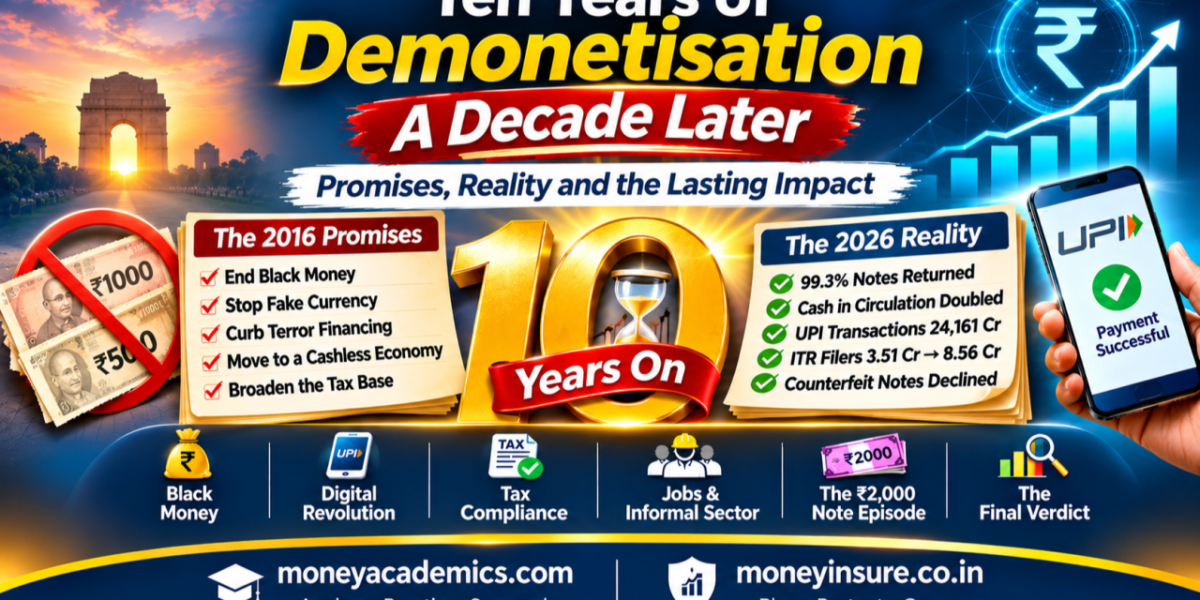
On November 8, 2016, Prime Minister Narendra Modi announced the withdrawal of the existing ₹500 and ₹1,000 currency notes, which represented approximately 86% of the value of currency in circulation. The decision, popularly known as notbandi, was presented as a major step against black money, counterfeit currency, corruption, and terror financing. Ten years later, demonetization remains one of India’s most controversial economic decisions. While supporters highlight increased digital transactions, greater financial transparency, and tax compliance, critics emphasize the severe cash shortage, disruption of informal businesses, and limited success in eliminating unaccounted wealth. It was not demonetization at all; rather it was re-monetization as new notes were issued in place of old ones.
The central question is: Did demonetization/re-monetization achieve its original objectives, and were its long-term benefits sufficient to justify its economic and social costs?
1. Original objectives versus actual outcomes
| Objective | Outcome after ten years | |
| a. | Eliminate black money | Approximately 99.3% of demonetized currency returned to the banking system; limited direct extinguishment of unreturned cash |
| b. | Reduce dependence on cash | Cash circulation increased substantially, although digital payments also expanded |
| c. | Promote digital payments | UPI became a major success, processing over 24,161 crore transactions in FY 2025–26 |
| d. | Broaden the tax base | Tax filings and collections increased, but the contribution of demonetization cannot be isolated from other reforms |
| e. | Eliminate counterfeit currency | Old notes were invalidated, but counterfeiting was not permanently eliminated |
| f. | Curb terror financing | Temporary disruption was plausible, but sustained long-term success is difficult to establish |
The outcomes indicate that demonetization produced some lasting changes in financial Behaviour, but its original objectives were not uniformly achieved.
2. Black money: Did demonetization deliver?
One of the principal objectives was to uncover and eliminate unaccounted wealth held in cash. According to the Reserve Bank of India’s 2017–18 Annual Report, approximately
₹15.31 lakh crore of the ₹15.42 lakh crore in demonetized notes returned to the banking system, representing about 99.3%. This meant that very little of the withdrawn currency was permanently extinguished through non-return.
However, the return of currency does not automatically establish that every deposit was legitimate. Deposits could create financial records for tax scrutiny, although their effectiveness depended on subsequent investigation and enforcement. A more fundamental limitation was that black wealth is not necessarily held as cash. It may be stored in real estate, gold, financial assets, overseas holdings, or concealed business transactions. Therefore, demonetization could disrupt certain cash holdings but could not eliminate the underlying causes of tax evasion and corruption.
The lesson: Black money is primarily a problem of concealed income, weak enforcement, and institutional practices—not simply the existence of high-value currency notes.
3. The cash paradox: Digital growth without a cashless economy
One of the most striking developments over the decade has been the simultaneous growth of cash circulation and digital payments. Currency in circulation increased from approximately
₹17.77 lakh crore in November 2016 to ₹43.16 lakh crore by October 23, 2026. This represents an increase of approximately 143% in nominal terms.
However, the absolute increase should not be interpreted as proof that cash dependence rose by the same proportion. Population growth, inflation, nominal GDP expansion, and changes in payment behaviour must also be considered. India’s experience demonstrates that digital payments and physical cash can coexist. Cash remains useful for informal transactions, emergencies, certain rural activities, and people with limited access to digital infrastructure.
Consequently, demonetization did not establish a cashless economy, although India made considerable progress towards a more digitally connected payment system.
4. Digital payments: A major transformation
India’s Unified Payments Interface (UPI), launched in April 2016, has become one of the country’s most significant financial innovations. Government and NPCI data show that UPI processed approximately 24,161.69 crore transactions worth ₹314.23 lakh crore in FY 2025–
26. Digital payments have expanded across retail shops, street vendors, transport services, educational institutions, and online commerce. Demonetization may have encouraged some consumers and businesses to experiment with digital alternatives during the cash shortage. However, smartphones, affordable mobile Internet, interoperable payment technology, banking access, merchant adoption, and continuing improvements in digital infrastructure also drove UPI’s subsequent growth. It would therefore be inaccurate to attribute the entire digital payments revolution to demonetization.
The major achievement was the expansion of India’s digital payment ecosystem, but its success reflects several technological and institutional developments rather than one policy decision alone.
5. Formalization and Tax compliance
Demonetization required holders of withdrawn currency to deposit or exchange their notes through the banking system, creating transaction records that could assist tax authorities in identifying potentially unexplained deposits. During the following decade, India also experienced an expansion in income-tax filings, digital tax administration, banking access, and formal financial transactions. Supporters argue that demonetization contributed to greater financial transparency and encouraged participation in the formal economy. However, other developments—including the introduction of the Goods and Services Tax (GST), expanded information reporting, digital tax systems, economic growth, and changes in tax administration—also influenced these outcomes.
Moreover, depositing money into a bank account does not automatically transform an informal business into a formal enterprise. Sustainable formalization requires affordable compliance, access to credit, productive employment, reliable institutions, and incentives for businesses to operate within the formal system. Thus, demonetization may have assisted financial tracking, but its independent contribution to long-term tax compliance remains difficult to measure precisely.
6. Economic and Social costs of Demonetization
The immediate economic consequences were particularly severe because a large proportion of everyday transactions depended on cash.
a. Informal sector and employment
Small traders, street vendors, construction workers, agricultural laborers, and microenterprises experienced difficulties in making and receiving payments. Businesses
dependent on daily cash receipts faced liquidity shortages, while workers relying on cash wages experienced interruptions in employment and income.
b. Agriculture and rural economy
Farmers and agricultural traders faced payment difficulties during the transition. Rural households with limited banking facilities were especially vulnerable to cash shortages.
c. Consumption and production
Reduced cash availability affected purchases, business turnover, and working capital in cash-intensive sectors. Although economic growth slowed around this period, attributing a precise GDP loss solely to demonetization is difficult because other economic developments were occurring simultaneously.
d. Distributional consequences
The burden of adjustment was uneven. Households with limited savings, small businesses, and people lacking easy access to banks or digital payments faced greater difficulties. These costs are important when evaluating the policy because economic success should be measured not only by eventual technological progress but also by the disruption experienced during implementation.
- Counterfeit currency and the ₹2,000 Note
Demonetization immediately invalidated existing counterfeit copies of the withdrawn
₹500 and ₹1,000 notes. However, the introduction of new currency designs did not permanently eliminate counterfeiting. Counterfeit detection data must also be interpreted carefully because reported detections depend on circulation patterns, inspection intensity, and banking procedures. Following demonetization, the ₹2,000 note was introduced to facilitate re-monetization.
In May 2023, the RBI announced the withdrawal of ₹2,000 banknotes from circulation
under its Clean Note Policy. These notes continued to retain their legal tender status. The subsequent withdrawal illustrated the continuing adjustments required in India’s currency management system.
8. Was Demonetization economically justified?
A balanced assessment must distinguish between the policy’s original objectives, its immediate costs, and developments that occurred afterwards.
a. Arguments supporting demonetization:
- It created financial records of large currency deposits.
- It may have encouraged temporary adoption of non-cash payment methods.
- It provided opportunities for tax authorities to examine suspicious deposits.
- It signaled a strong policy commitment against unaccounted cash holdings.
b. Arguments questioning demonetization:
- Approximately 99.3% of the withdrawn currency returned.
- Cash continued to play a substantial role in the economy.
- Informal businesses and vulnerable workers experienced serious disruption.
- Counterfeit currency and black money were not permanently eliminated.
- Many subsequent improvements in tax compliance and digital payments cannot be attributed exclusively to demonetization.
The fundamental economic issue is whether comparable improvements in transparency, tax enforcement, and digital adoption could have been achieved through less disruptive measures.
9. Lessons for future economic policy
Demonetization offers important lessons for the design and implementation of major economic reforms.
First, policy objectives must be clearly defined. Governments should establish measurable targets before implementation rather than relying on changing interpretations of success.
Second, costs and benefits should be assessed together. Economic disruption, employment losses, administrative expenditure, and effects on vulnerable groups must be considered alongside potential long-term gains.
Third, institutional reform is more sustainable than sudden disruption. Effective tax enforcement, transparent financial transactions, digital infrastructure, and reduced compliance burdens can address structural weaknesses without necessarily requiring a major currency shock.
Fourth, implementation capacity matters. Banking infrastructure, cash availability, public communication, and transition arrangements are essential when policies affect millions of households and businesses.
Finally, independent evaluation is necessary. Major reforms should be reviewed through credible data and transparent analysis rather than political claims alone.
10. Conclusion: A decade of mixed outcomes
Ten years after demonetization, India’s experience presents a complex picture.
The policy did not eliminate black money, counterfeit currency, or dependence on cash. The return of nearly all withdrawn notes and the continuing importance of currency in everyday transactions demonstrate the limitations of using demonetization as a primary instrument against unaccounted wealth.
At the same time, India experienced remarkable growth in digital payments, financial connectivity, and tax administration. However, these achievements resulted from multiple reforms and technological developments, making it difficult to establish how much was caused by demonetization itself.
The immediate disruption to small businesses, workers, and cash-dependent households must also remain part of the evaluation.
Demonetization should therefore be judged neither solely by the growth of UPI nor solely by the return of withdrawn notes, but by whether its identifiable benefits outweighed its economic and social costs.
The broader lesson is that lasting economic transformation requires sound institutions, technological innovation, transparency, and carefully designed reforms—not merely dramatic policy announcements.